Canada's Proposed May 15 T1 Deadline: A 2028 Planning Guide for Accounting Firms
Canada's 2026 federal budget proposes a single May 15 filing and balance-due date for individual T1 returns, including returns for self-employed people and their spouses or common-law partners. If adopted as written, the change would apply to the 2027 and later taxation years. For accounting firms, that means the first season to plan around would be the filing of 2027 returns in 2028—not the 2027 filing season.
The proposal matters because self-employed clients currently have a later filing deadline than most individuals. For 2026 tax returns filed in 2027, the Canada Revenue Agency lists June 15, 2027 as the filing deadline for self-employed people, while balances owing remain due April 30. The budget proposal would move the self-employed filing date earlier to May 15 for 2027 and later tax years, while setting May 15 as the filing and payment date for all individuals. The budget is a proposal; a budget statement by itself does not enact a tax-law change. Firms should keep current deadlines in client instructions until the measure is enacted and official guidance is updated.
What the proposal could change for a firm's calendar
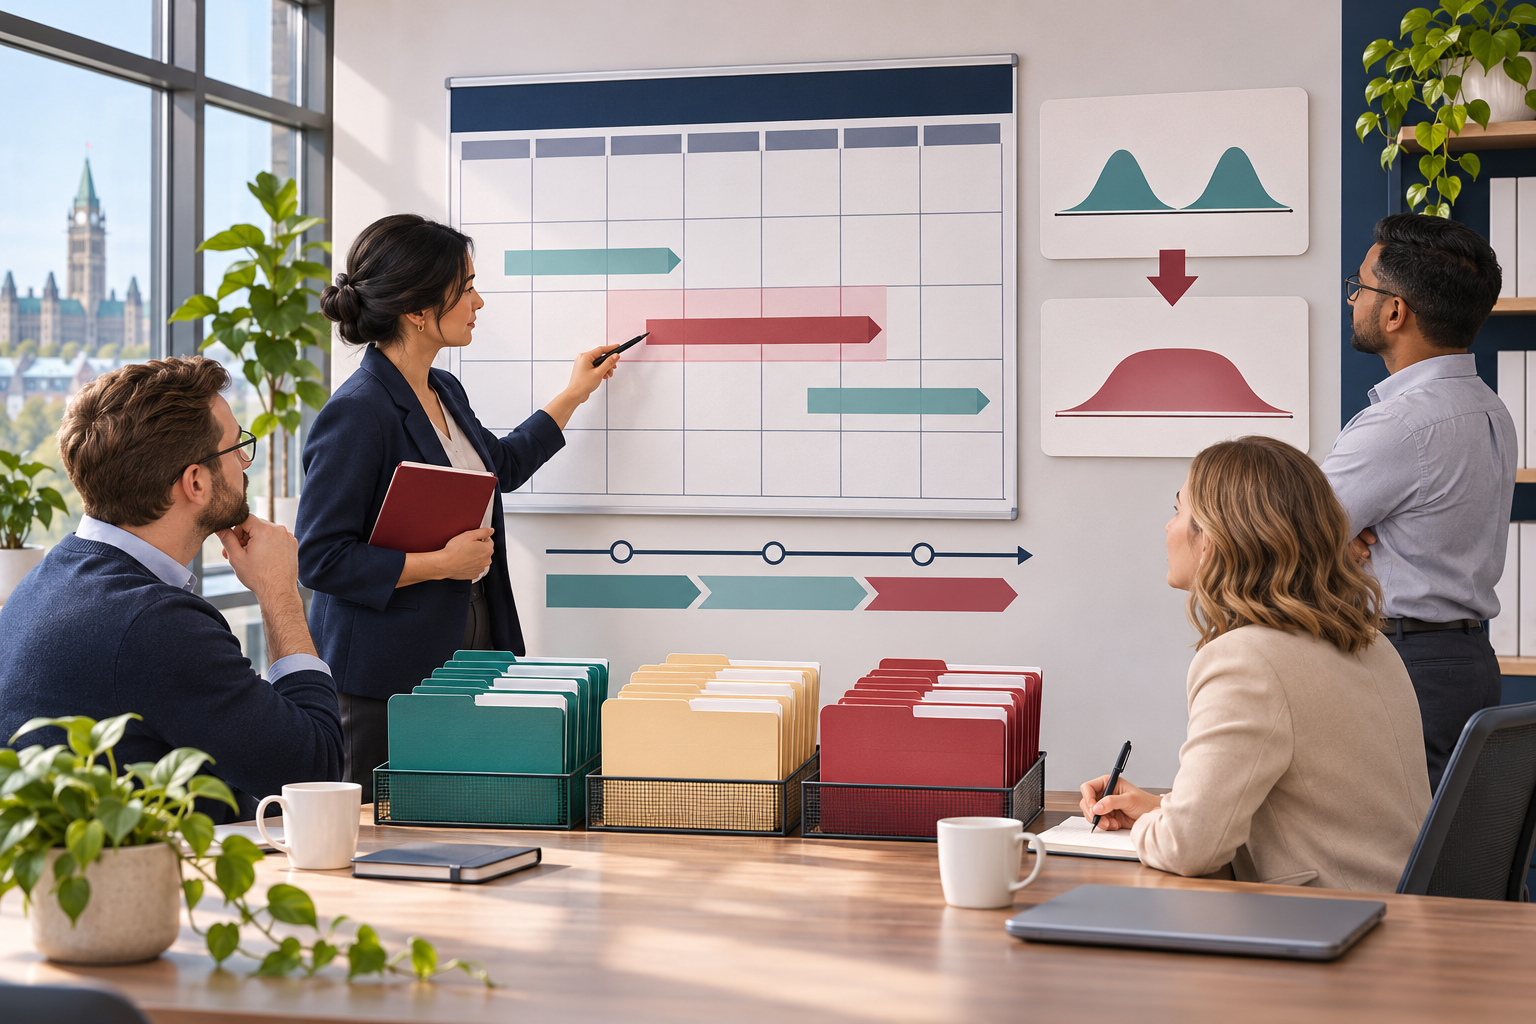
If the proposed date takes effect, the familiar two-wave T1 season would change. Firms would have a single May 15 deadline across individual returns rather than an April 30 date for most clients followed by a June 15 filing date for self-employed clients. That does not automatically mean every return should be scheduled for the same week. It does mean that firms may need to revisit how they segment work, assign preparers and reviewers, and identify client files that are at risk earlier in the season.
Do not move every client milestone today. The proposal applies to 2027 and subsequent taxation years, and it may change during the legislative process. For the 2027 filing season, follow current CRA dates. For the 2028 season, build a conditional plan that can be revised once legislation and CRA guidance confirm the operative dates.
A practical planning sequence for firms
1. Map the clients affected by a shorter self-employed window
Separate individual files by the work pattern that affects delivery: standard T1s, self-employed returns, returns with business income, and files that depend on information or approvals arriving later. This is an internal capacity map, not a promise to clients about the final law. For each group, note the expected preparer, reviewer, and decision-maker, plus the information needed before work can begin.
2. Work backward from a conditional May 15 date
Choose internal milestones for document requests, preparation, review, client follow-up, signature or approval, and final filing. Set these as planning assumptions for the 2028 scenario, then mark them as provisional. A target deadline is only useful if the team can see which prerequisite is missing and who owns the next action.
3. Check team capacity and review capacity separately
Preparation hours do not tell the whole story. A file can be ready for review while the reviewer is already full. Estimate work by staff member and review stage, identify weeks where several high-effort files land together, and decide in advance who can take overflow or cover an absence. Review this alongside the firm's existing busy-season plan; Awditify's broader capacity-planning guide covers the general workflow.
Awditify's in-app Practice guides describe T1 return records with a due date, preparer, reviewer, partner and budgeted hours, plus staff assignment and workload views. Those fields can support a firm's internal scenario plan: assign ownership, compare work against budgeted time, and make a review bottleneck visible while there is still room to respond. They do not determine tax law or replace professional judgment.
4. Give each exception an owner and next step
When a file is waiting on a client, a missing document, an internal review or a decision, record the blocker and its owner. Use a short weekly exception review to ask: which files have no preparer or reviewer, which are waiting on information, and which are nearing their internal milestone? A clear queue helps managers intervene before an external due date becomes the first sign of trouble.
5. Update the client message only when dates are confirmed
Prepare a reusable explanation of the proposal, but do not send it as though May 15 were already the rule. Once the government enacts the change and CRA guidance confirms how it applies, update engagement communications, client reminders, intake deadlines and internal calendars together. If the proposal changes, revise the plan before communicating a new date.
A simple scenario checklist
- Keep the current published dates in force for work due in 2027.
- Create a separate, clearly labelled 2028 planning scenario for a possible May 15 common T1 date.
- Identify self-employed client files and their information dependencies.
- Assign a preparer, reviewer and partner; estimate hours where the firm's process supports it.
- Check weekly capacity by both preparation and review stage.
- Set internal milestones earlier than the external due date, then review exceptions regularly.
- Confirm enacted legislation and CRA guidance before changing client-facing dates.
The proposed date is a reason to check the workflow now, not a reason to promise a deadline that has not yet been confirmed. Firms that can see ownership, readiness, budgeted effort and review capacity can adapt the plan when the final rules are known.
If your firm is reviewing its T1 workflow for the 2028 season, book an Awditify demo to see how deadlines, staff assignment and review work fit together in Practice.
Sources
- Department of Finance Canada — Budget 2026 tax measures (November 5, 2026; accessed November 9, 2026).
- Canada Revenue Agency — 2027 tax deadlines for businesses and self-employed individuals (accessed November 9, 2026).
- House of Commons of Canada — Financial Procedures (accessed November 9, 2026).
Discussion
Comments